Global Payments 9 min read
Japan Payment Landscape: JCB, PayPay, and the Cash-Heavy Market Guide
How payments actually work in Japan: JCB and global cards, PayPay and QR wallets, konbini cash, and what cross-border operators need to accept them locally.
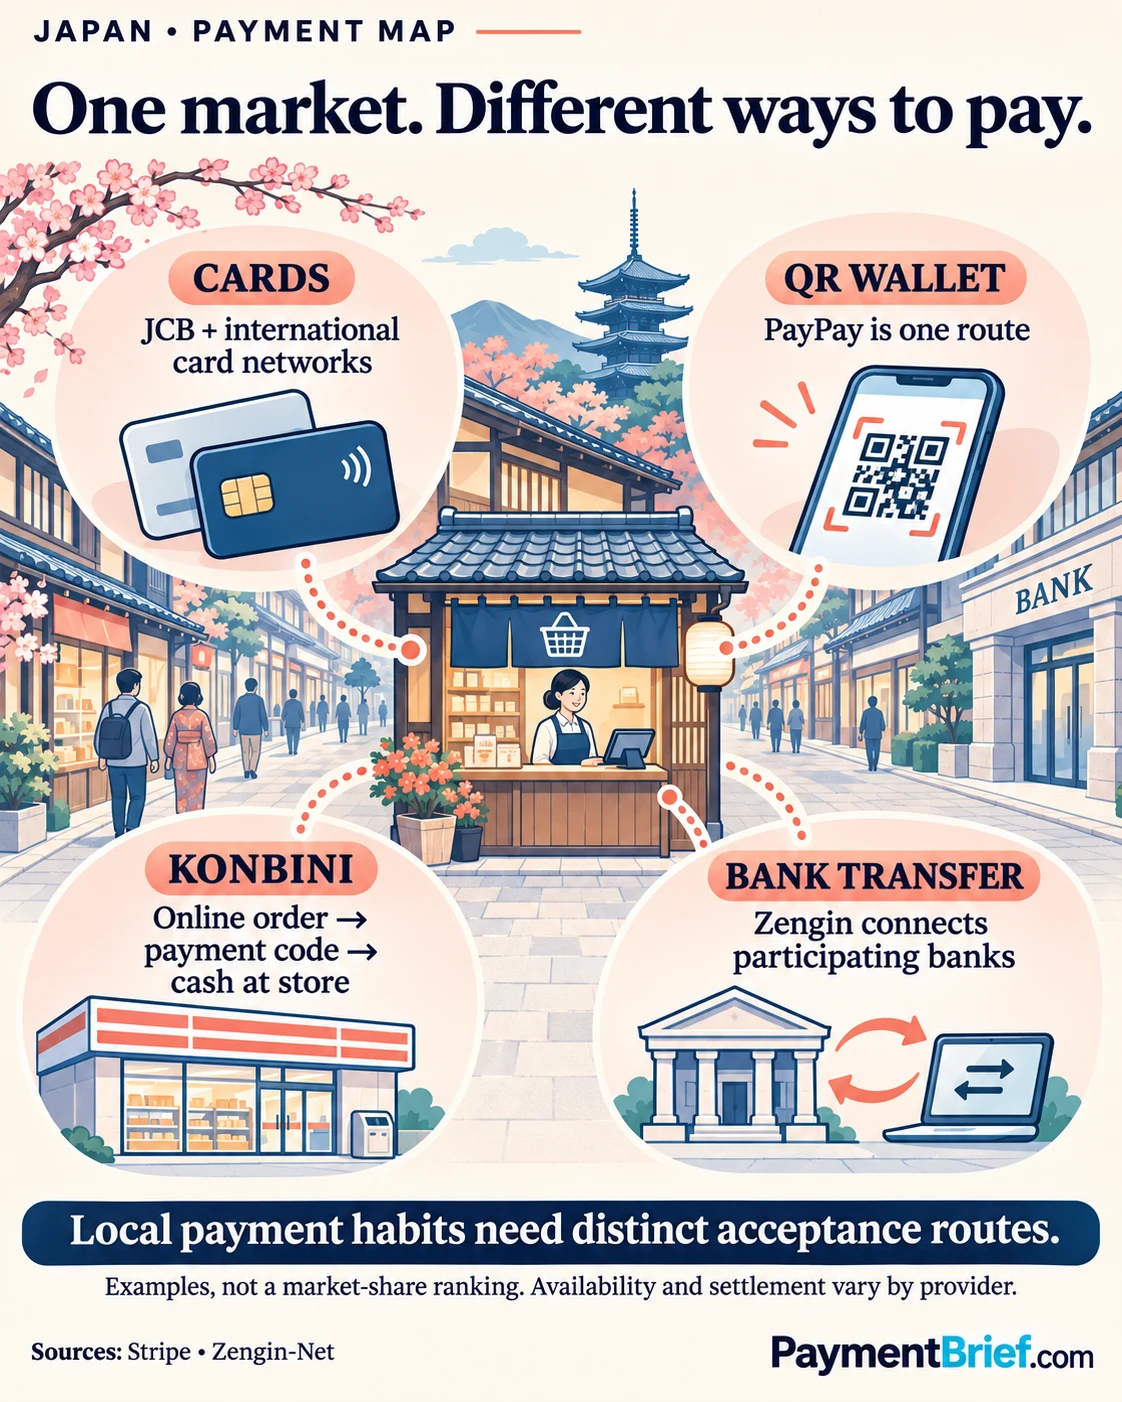
Japan's cashless ratio reached 42.8% in 2024. Operators can assess JCB, QR payments such as PayPay, konbini and bank transfers as distinct acceptance options; availability and processing depend on provider and bank arrangements.
Japan's cashless payment ratio reached 42.8% in 2024 (Japan Ministry of Economy, Trade and Industry, March 2025), so cash remained a substantial part of consumer payment value. This guide focuses on several distinct payment options and infrastructure roles relevant to operators: cards, QR payments such as PayPay, convenience-store payments and bank transfers.
For a foreign payment operator, the practical question is which of these methods its target customers use and which are available through its acquirer or payment provider. JCB is a Japan-origin card network with international acceptance. PayPay is one QR payment option. Konbini lets customers pay for some online purchases in cash at participating stores, while Zengin is the domestic interbank transfer system. These methods have different provider, bank and merchant requirements; they do not form one mandatory acceptance stack.
JCB: The Domestic Card Network
JCB (Japan Credit Bureau) is a Japan-origin card network with international acceptance. Founded in 1961, JCB issues cards directly (JCB-branded credit and debit cards) and operates a card network accepted at JCB-affiliated merchants globally.
For operators, the acceptance check is whether the acquirer supports JCB for the relevant sales channel and merchant. Card-network availability and routing depend on the merchant's acquiring arrangement.
Acquiring JCB Acceptance
Outside Japan, JCB acceptance may be available through network partnerships, including the JCB-Discover alliance. The exact route depends on the market and the acquirer's network connections. Operators should confirm JCB acceptance with their acquirer for each target market.
For domestic Japan acceptance, confirm whether JCB acquiring is included in your acquirer or PSP arrangement and whether a separate agreement or configuration is needed. Coverage varies by provider and sales channel.
JCB's 3DS implementation: JCB's 3DS (3-D Secure) authentication is branded "J/Secure." Operators implementing 3DS for card-not-present transactions in Japan must ensure their payment service provider supports J/Secure alongside Visa Secure and Mastercard Identity Check.
PayPay: A QR Payment Option
PayPay is a QR payment service in Japan. Launched in 2018 as a joint venture between SoftBank and Yahoo! Japan (now LY Corporation), it supports merchant-presented and customer-presented QR flows.
PayPay operates as a QR code payment system. Merchants display a PayPay QR code; customers scan with the PayPay app and authenticate with a PIN or biometric. The payment routes from the customer's PayPay balance (which can be topped up from a bank account, credit card, or convenience store cash deposit) to the merchant's PayPay account.
PayPay merchant fees: Published merchant pricing varies by merchant size and product. Confirm current fees and terms with PayPay or the acquiring provider; do not infer merchant savings or adoption effects from headline rates alone.
PayPay for foreign operators: Availability for e-commerce or in-app use depends on the merchant's provider, eligibility and integration terms. Confirm supported payment flows, confirmation and refund handling with the selected provider before planning the integration.
PayPay Bank (formerly Japan Net Bank): PayPay's banking arm offers banking services to PayPay users, including a funding route for PayPay balances. Product availability and eligibility depend on the user's account and provider terms.
Convenience Store Payment Networks
Japan's convenience stores also serve as payment points for utility bills, insurance premiums, tax payments, online purchase settlement, and cash deposits. 7-Eleven Japan, FamilyMart, and Lawson are among the major chains.
Convenience store payment for e-commerce: A Japanese consumer making an online purchase can select "convenience store payment" at checkout, receive a payment code, and pay cash at a participating store. Payment instructions and code validity periods depend on the provider. The merchant receives confirmation after the store processes payment; payout timing and refunds follow the provider's terms. For example, Stripe says funds from its Japan Konbini payments become available after four business days.
Major convenience store payment service providers: FamilyMart operates FamiPay (its own QR/wallet brand); Lawson uses Ponta and au PAY integration; Ministop is part of the Aeon group with separate payment systems. The older "konbini payment" infrastructure for online purchases is delivered to foreign merchants via intermediaries like Degica (multi-konbini aggregation), Komoju (GMO-owned, convenience store payment API), and Stripe (konbini support in Japan).
Other contactless payments at convenience stores: Transit-linked prepaid IC cards such as Suica and PASMO store value and can also pay at participating shops. iD and QUICPay are separate contactless payment services; their funding and settlement depend on the card or account linked to the service. In-person acceptance depends on the merchant's terminal and supported payment methods.
The Zengin Real-Time Rail
Zengin (全国銀行データ通信システム) is Japan's domestic interbank funds transfer system, operated by the Japanese Bankers Association. It supports transfers between participating financial institutions.
Zengin operates in two modes:
- Batch processing: Traditional mode, settlement during banking hours on business days
- Zengin More Time System (launched October 2018): Extends transfer processing into weekday evenings, weekends, and holidays at participating banks.
The More Time System extends the hours in which participating banks can process transfers. Availability and credit timing depend on the sending and receiving banks, so operators should confirm the relevant service conditions with their bank or PSP. For comparison with other real-time systems, see the real-time rail comparison across Pix, UPI, SPEI, and PromptPay.
For operators: Bank transfers are one option for business invoices and other account-to-account payments. Confirm whether your bank or PSP supports the required Zengin flow and what account, confirmation, and settlement conditions apply.
Access to Zengin transfers for an operator depends on its bank or PSP arrangement. Ask the provider about supported flows, confirmation method, payout timing and reconciliation details.
Practical Guidance: What Foreign Operators Need
For a foreign operator building Japanese payment acceptance in 2026:
Card acceptance (baseline): Check that the acquirer supports Visa, Mastercard, and JCB for the intended sales channel. Confirm whether the PSP supports J/Secure (JCB's 3DS) where applicable.
PayPay (high priority for consumer-facing): For operators serving Japanese consumers, assess whether PayPay is available for the intended sales channel and customer journey. Check method support, merchant eligibility, and integration terms with the selected provider.
Konbini payments (cash-optional): For consumer e-commerce, assess konbini payment against your customer mix and provider terms. Payment-code validity, order holds, refunds, and payout timing vary by integration; for example, Stripe documents four business days before funds are available for its Konbini method.
Bank transfer (B2B and high-value): Bank transfer is commonly used for invoiced payments in Japan. For B2B collection, confirm whether your Japanese bank account or PSP-provided virtual account supports the required Zengin transfer flow and what confirmation timing applies. More Time extends processing hours at participating banks; it does not guarantee real-time confirmation for every provider or transaction.
JCB acceptance for physical merchants: Confirm with your acquirer that the terminal and merchant account support JCB for the intended in-person payment flow.
Cash and Digital Payment Options
Japan reported a 42.8% cashless-payment ratio for 2024 (METI, March 2025). This market-wide measure does not identify which payment methods are suitable for a particular merchant.
Konbini payments provide a cash option for online purchases. Assess their value against your customer mix and provider terms.
PayPay is one established QR/app payment option alongside JCB and other cards, Suica/IC cards, bank transfers, and konbini payments. Operators should choose acceptance methods based on their target customers and the support available from their acquirer or PSP.
What This Means for Operators
Japan has several distinct acceptance options, including JCB, PayPay, konbini, IC cards, and Zengin transfers. Some PSPs aggregate multiple methods, but coverage varies by product and merchant eligibility; confirm which methods, flows, and settlement arrangements are included before relying on a single integration.
For operators entering Japan, assess JCB, PayPay, and konbini against the target customer journey, merchant eligibility, integration effort, and provider terms. No single order of priority fits every business model.
For operators already in Japan, compare payment-method performance in your own checkout data before estimating the effect of adding or changing an acceptance method.
 By Shaun Toh · Director, Digital Payments · Razer