Payments Economics 9 min read
Card Scheme Fees Demystified: What's Inside the MDR
Understand the main layers in card acceptance costs and what the UK PSR found about scheme and processing fees charged to UK acquirers.
Card pricing combines interchange, scheme fees and processor charges. The UK PSR found average core scheme and processing fees, relative to transaction value, rose at least 25% in real terms from 2017 to 2023. This is a UK finding, not a global MDR trend.
The MDR on an acquiring statement may combine multiple cost layers. A useful simplified model separates interchange, scheme fees and the acquirer or processor's charges. How these appear depends on the pricing structure and contract. The UK Payment Systems Regulator (PSR) has documented growth in a defined set of scheme and processing fees charged to UK acquirers; that does not establish a comparative growth ranking for all card acceptance costs.
This article explains the main fee layers, the limits of public fee information and questions operators can ask when reviewing their own pricing.
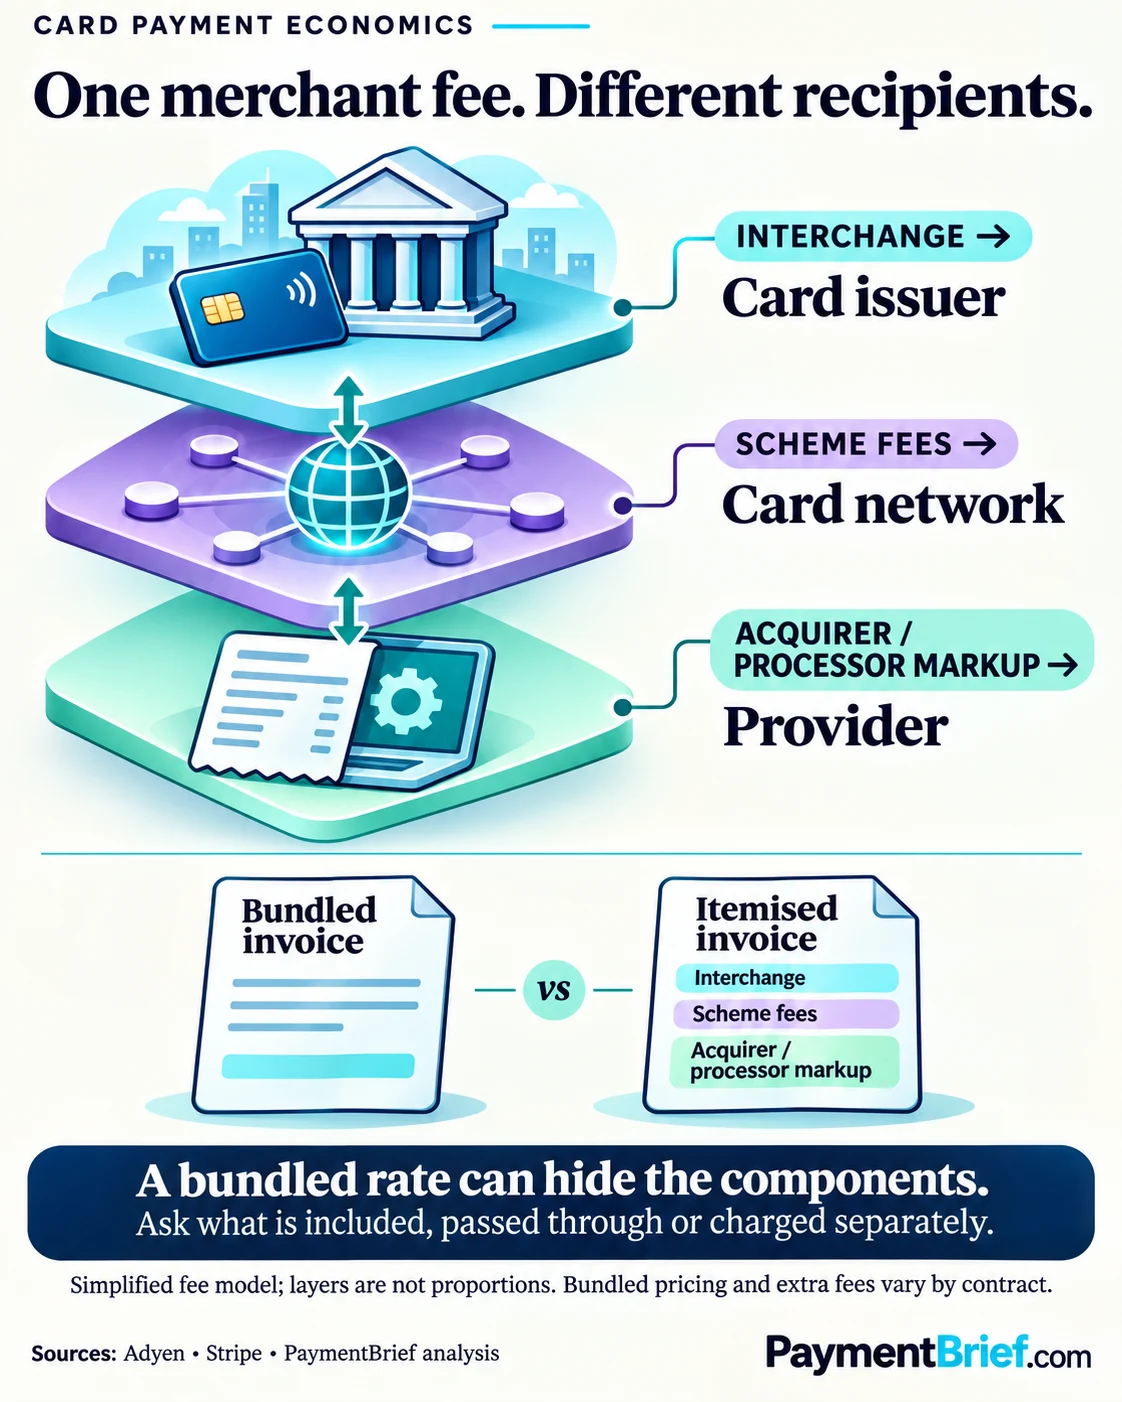
The Three-Layer MDR Stack
A card transaction fee paid by a merchant to their acquirer breaks down into:
Layer 1: Interchange — the fee paid to the card issuing bank. Interchange is set by the card networks (Visa, Mastercard) and varies by card type (consumer, commercial, premium rewards), transaction type (card-present, card-not-present, recurring), and geography. In the EU, interchange is regulated at 0.2% for consumer debit and 0.3% for consumer credit under the Interchange Fee Regulation (IFR), applicable to domestic and intra-EEA consumer card transactions only — commercial cards and non-EEA issuers are not capped. In the US, debit interchange splits along the Durbin Amendment line: cards issued by banks with $10B+ in assets are Durbin-regulated and capped at $0.21 + 0.05% of the transaction, plus a further $0.01 fraud-prevention adjustment for issuers that meet the Fed's fraud-prevention standards. On a $50 ticket that ceiling is $0.21 + (0.05% × $50 = $0.025) + $0.01 = $0.245, not the ~$0.22 sometimes quoted from an incomplete sum. Cards from issuers under $10B are Durbin-exempt and are not subject to the regulated cap. Credit interchange is unregulated for all US issuers. Visa and Mastercard do not publish their full interchange and fee schedules in a form that supports citing precise unregulated Durbin-exempt debit or premium-credit rates with confidence — published third-party estimates vary too widely across sources to state a specific range here without repeating that same sourcing problem. Every regulated market caps interchange through a different mechanism and with different carve-outs — see interchange regulation by market for how the EU, UK, US, Australia, Brazil, and India regimes actually differ, and where each one stops applying.
Layer 2: Scheme fees — fees paid to the card networks themselves (Visa and Mastercard as network operators). Scheme fees are separate from interchange, assessed on top of it, and paid by the acquirer — who passes them through to the merchant either blended into a flat MDR or itemized in interchange-plus pricing. This layer is the subject of this article and the most opaque part of the stack.
Layer 3: Acquirer or processor charges — the provider's own charges or markup. A bundled price may not show these separately; an interchange-plus arrangement may itemise some components. The exact treatment depends on the agreement and statement.
Scheme Fee Categories and Visibility
The UK PSR's market review concluded that information acquirers receive from Mastercard and Visa can be insufficient to understand the fees charged, and some acquirers reported difficulty accessing information through scheme portals. This is evidence about the UK review and the information available to acquirers; it does not establish that every merchant statement lacks detail or that all fee schedules are unavailable.
Fee schedules may include charges for network assessments, access or processing, cross-border activity, digital services and specific transaction types. Their names and application vary; check the current schedule and your contract.
Network fees
Networks may charge assessment or other network fees. Applicable rates and calculation bases vary by network, product, geography and contract; consult the current schedule available to your acquirer rather than relying on a generic percentage.
Cross-Border Fees
Cross-border pricing may depend on merchant and issuer locations, currency conversion and other transaction details. The applicable scheme and acquirer schedules determine the classification; do not infer a fee from geography alone.
Ask your acquirer how the relevant scheme defines cross-border transactions, whether conversion affects classification, and which additional provider charges apply. These details can differ across arrangements.
Service and technology fees
Fee schedules may also include charges related to digital services, access, authorisation, merchant locations or specific transaction types. Names and applicability differ across schedules; obtain current fee definitions and statement mapping from your acquirer.
Check whether a listed fee is assessed by the network, acquirer or processor, how it is calculated, and whether it is passed through or bundled. Do not infer a provider's margin or a network's strategy from the line item's name alone.
Transaction-specific fees
Schedules may set different treatment for recurring, cross-border, reversed, disputed or other transaction types. Verify current applicability, amount and liable party in the relevant rules and contract.
How Much Have Scheme Fees Grown?
The PSR reported that Visa and Mastercard's average core scheme and processing fees to UK acquirers, measured as a proportion of transaction value, grew by at least 25% in real terms between 2017 and 2023. This is a defined UK-market finding about fees charged to acquirers, not a global growth rate, merchant MDR increase or ranking against interchange and acquirer charges. For other markets and periods, use the relevant regulator's evidence and current contract data; do not extrapolate this result.
What Operators Can Do
Operators can improve visibility into their own acceptance costs and assess options available under their contracts and local rules:
Least-Cost Routing (LCR)
Least-cost routing may be available for eligible debit transactions in markets with multiple networks. Availability, eligible transactions and cost effects depend on the market, payment setup and provider.
The RBA's 31 March 2026 conclusions paper maintained an expectations approach for LCR and said there was not a strong case for a formal requirement in the in-person environment. RBA research has also compared debit acceptance costs for merchants with and without LCR. These are Australian findings; they do not guarantee a saving for an individual merchant. Check which transactions qualify and compare actual costs under your acquirer setup.
In the US, Regulation II includes debit routing requirements for covered issuers and transactions. Which routing options a merchant can use and whether they reduce cost depend on the card, transaction, checkout and acquirer configuration. Confirm eligibility and expected effect with the acquirer.
Surcharging and Payment Method Steering
Surcharging — passing the card acceptance cost to the cardholder as a separate line item — is subject to local law, network rules and provider terms. Where permitted, it may affect the merchant's net acceptance cost and customer choices; check the applicable requirements and evaluate the result.
Customer response and total economics vary by market and business model.
Payment method steering — presenting multiple payment methods — may affect the payment mix. Legal and network requirements, provider availability and customer response differ by market; evaluate the actual cost and conversion effects.
Interchange Optimization
Interchange is distinct from scheme fees, though operators may review both as part of acceptance cost. Ask whether transaction attributes and additional data affect qualification under the applicable rate schedule, and request evidence in your own transaction reporting. Do not assume that a data field or channel change guarantees a lower rate.
Volume-Based Scheme Fee Tiers
Ask your acquirer whether your agreement includes volume tiers, rebates or other negotiated terms and what conditions apply. Do not assume a particular threshold or that a direct network agreement is available.
Interchange-Plus vs Blended Pricing
Under a blended price, several cost components may be combined. An interchange-plus arrangement may itemise interchange, scheme fees and a provider markup, depending on the agreement and statement:
- You see actual interchange on each transaction (varies by card type)
- You see actual scheme fees (varies by transaction type, geography)
- You pay a fixed acquirer margin on top
An itemised structure may improve visibility but does not by itself guarantee a lower total price. Compare complete charges, eligible transactions and services under both offers using the same transaction mix.
What This Means for Operators
Fee schedules and provider pricing can change. The PSR's UK finding does not establish which card-acceptance component is growing fastest or predict future growth. Operators should review current statements and contract terms with their acquirer.
Practical review:
For any volume: Ask your acquirer to map statement lines to the contract, clarify pass-through and bundled charges, and explain changes since the previous period.
Where alternatives are available, compare complete pricing offers and eligible routing options using your actual transaction mix. Savings are not guaranteed and depend on contract, market, routing eligibility and operating costs.
Sources & methodology (5)
Regulation II debit interchange cap: an issuer's interchange fee may not exceed $0.21 plus 0.05% of the transaction value, plus a further $0.01 fraud-prevention adjustment for issuers that meet the Board's fraud-prevention standards — on a $50 ticket that is $0.21 + $0.025 + $0.01 = $0.245
Checked:
The RBA has never mandated least-cost routing; its 31 March 2026 Conclusions Paper reaffirms a non-binding 'expectations' approach, stating 'there is not a strong case for a formal regulatory requirement to enable LCR in the in-person environment' and maintaining 'the status quo with the "expectations" approach'. The RBA's own expectations timeline: industry encouragement began 2017; a general in-person/online LCR expectation was set in 2021; a narrower 2022 expectation addressed mobile wallet transactions specifically, targeting end-2024 availability
Checked:
RBA research (using merchant-level data) found the cost of accepting debit card transactions is nearly 20% lower for merchants with LCR enabled compared with those without
Checked:
The PSR's market review of card scheme and processing fees found that 'the information that acquirers receive from Mastercard and Visa can be insufficient to understand the fees they are charged', and reported 'Acquirers reporting difficulty in accessing relevant information through online portals provided and operated by the card schemes'. It concluded that acquirers' abilities to access, assess and act on relevant pricing information is below what would be expected in a well-functioning market
Acquirer-facing fee information: insufficient and hard to access
Evidence about the quality of the information the schemes give their own customers. It is not evidence that the full fee schedules are contractually confidential, and this article no longer says they are.
Checked:
UK Payment Systems Regulator market review found Visa and Mastercard's average core scheme and processing fees to acquirers, measured as a proportion of transaction value, grew by at least 25% in real terms over 2017–2023
Checked:
Source types explained in our Methodology.
 By Shaun Toh · Director, Digital Payments · Razer