Global Payments 7 min read
Brazil's PIX: What Payment Operators Entering LatAm Must Understand
Plan Pix acceptance in Brazil: pricing, payment confirmation, refunds, provider access and the difference between local collection and overseas payout.
Pix supports real-time domestic transfers, but a merchant integration still needs a provider quote, reliable payment confirmation, linked refunds and a clear payout contract. Consumer fee exemptions do not make merchant acceptance free.
Brazil's Pix is an instant-payment system that supports transfers around the clock. For a merchant entering the market, distinguish the payment reaching the receiving account from the provider making funds available to the merchant under its contract. A fast rail does not establish a free acceptance service, an immediate overseas payout or freedom from fraud-related recovery.
Start a provider comparison with four questions: who receives the money, what confirms a completed payment, how a refund is linked to that payment, and when the merchant can use or withdraw the proceeds. Those answers determine the integration and operating model more directly than a headline adoption statistic.
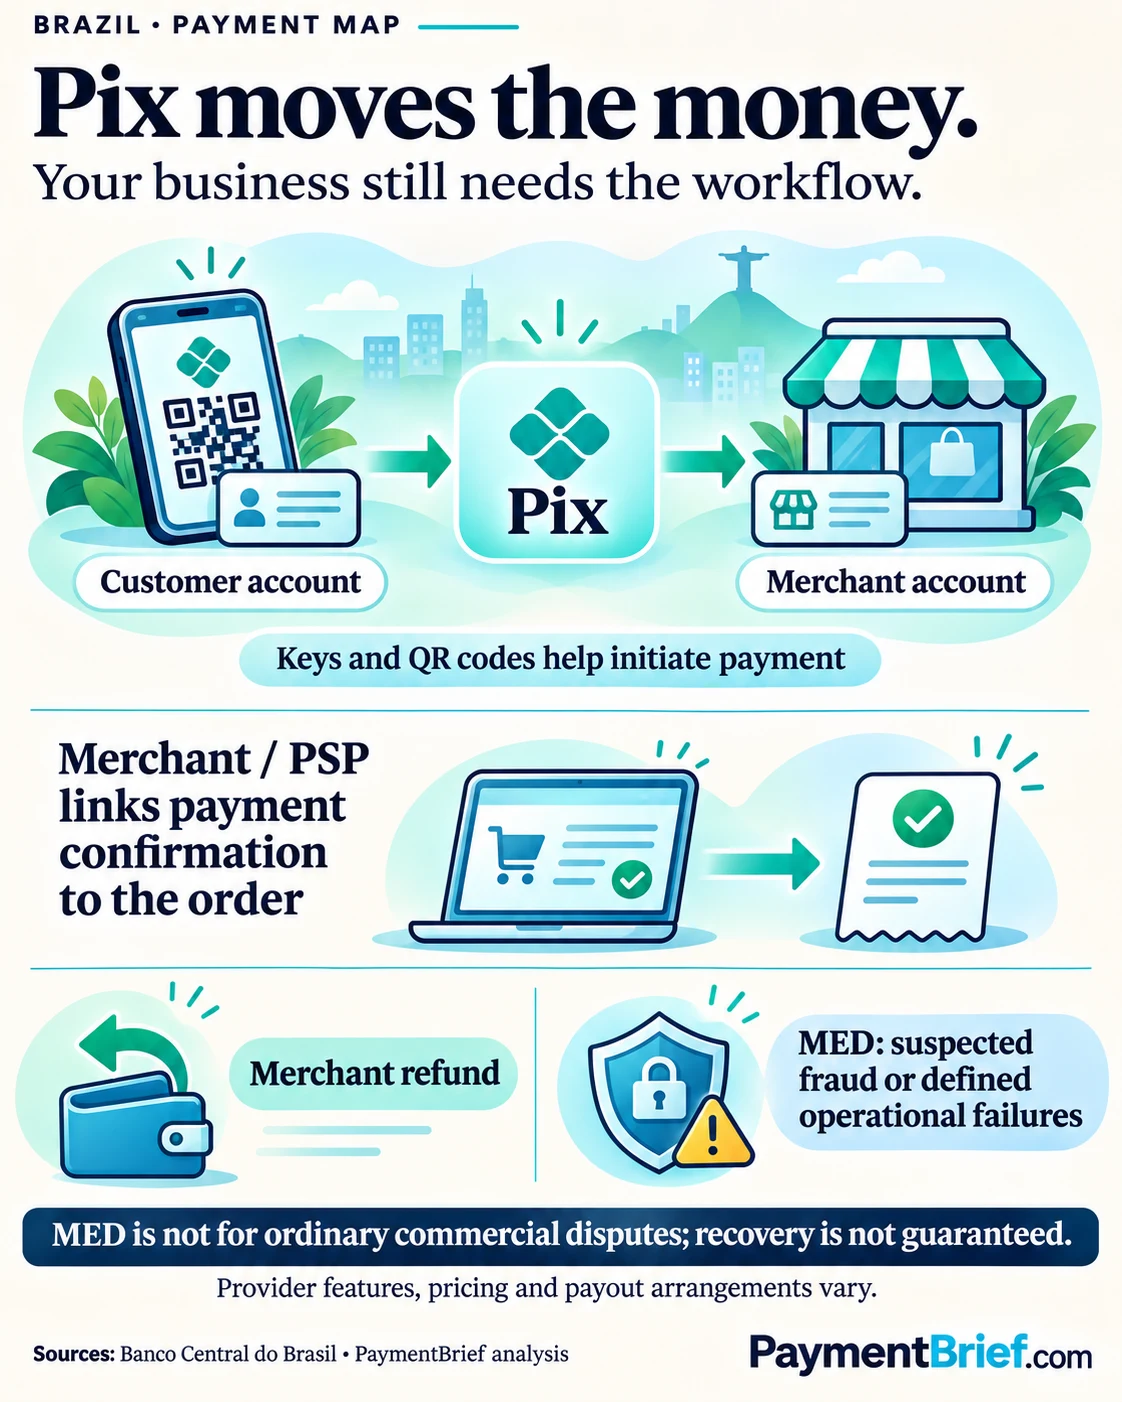
How Pix Fits a Merchant Checkout
The Banco Central do Brasil (BCB) describes Pix as real-time account transfers available every day, including weekends and holidays. Customers can use a registered key, account details, QR code or supported payment-initiation journey. Pix Cobrança supplies a collection mechanism; it is not a guarantee that a selected provider exposes every API feature.
The BCB's API Pix specification is for services offered by the receiving PSP. It covers collection requests, received payments, returns and recurring collections. Access to functions depends on the receiving customer's contract. A merchant connecting to a PSP API is not thereby becoming a direct participant in the central bank's settlement infrastructure.
Separate these records in the integration:
| Record | What the operator should retain | What it does not prove |
|---|---|---|
| Order | Order reference, amount, currency and expiry policy | That the customer has paid |
| Collection request | Provider reference, amount and checkout instructions | That the receiving account was credited |
| Payment confirmation | Confirmed identifier, amount and timestamp from the provider | That an overseas payout has completed |
| Return | Original payment reference, return identifier, amount and state | That a return request has completed |
| Merchant payout | Ledger entry, deductions and bank credit reference | That every underlying order was matched |
This is an operating checklist, not a promise that every PSP uses identical field names. Ask for sample payloads and reports before committing engineering work. The A2A merchant acceptance reference covers the wider architecture across account-to-account rails.
Confirmation and reconciliation
Treat the provider's verified payment state as the fulfilment trigger. A screenshot, displayed QR code or browser returning to a success page is not adequate evidence by itself. Build a recovery path for a missing notification: query the payment, match its amount and reference, then decide whether fulfilment can proceed.
Keep reconciliation idempotent. Receiving the same notification twice must not create a second paid order. Conversely, two actual payments against one order require an exception decision, not silent deletion of the second receipt. Test late payment after checkout expiry, unexpected amounts, duplicate notifications and provider downtime with the contracted service.
A customer may see a completed debit while the order remains pending because a callback failed. Support needs a payment identifier and access to the provider record. Asking the customer to pay again before checking creates a duplicate-collection risk.
Merchant Pricing: Obtain the Actual Quote
Pix merchant acceptance is not universally free. The BCB's tariff explanation distinguishes consumer exemptions from business charging and allows institutions to set fixed or percentage prices. Consumer exemptions also have exceptions; a payment described as free for a person is not evidence of a zero merchant fee.
Compare quotes on the same basket of transactions. Request the collection fee, minimum charge, refund treatment, payout charge, currency conversion and any monthly or integration costs. Keep domestic BRL collection separate from an international merchant's settlement package. A provider's price for that package is not a central-bank tariff.
Suppose two fictional quotes charge R$0.80 per receipt and 0.6% per receipt, with no other costs in this simplified illustration. At R$50 the percentage quote costs R$0.30; at R$500 it costs R$3.00. The flat quote costs R$0.80 in either case. These are assumed inputs, not market prices. The comparison depends on transaction values and additional fees.
A processing saving also needs to survive checkout completion and support costs. Compare completed-order rates, unexplained pending payments and refund workload in a controlled pilot. A provider's merchant cohort or marketing result is not an expected outcome for every Brazilian merchant.
Refunds, Fraud and Settlement Finality
Pix includes a return capability associated with the original payment: the API provides a return resource under the received payment's end-to-end identifier. Use the provider's supported linked-return workflow for a merchant refund, rather than assuming it must be an unrelated transfer to a key supplied by a claimant. Confirm the supported time window, balance requirements, partial-return handling and completion status.
Keep ordinary refunds separate from the Mecanismo Especial de Devolução (MED). BCB describes MED as a mechanism for suspected fraud and operational failures, not an ordinary commercial-disagreement process. Recovery depends on the case and available resources. Neither immediate settlement nor the absence of a card-style chargeback makes a receipt immune from a fraud-related block or return.
Maintain separate support routes:
- Cancellation or returned goods: check the original order and payment, then follow the merchant refund process.
- Suspected scam or account compromise: preserve records and escalate through the provider's fraud process.
- Unmatched receipt: reconcile before deciding whether to fulfil or refund.
- Payment to an unintended recipient: refer the payer to their institution; do not promise the merchant can reverse an unrelated transfer.
Record the support decision and final money movement separately. An approved refund request is not a completed refund.
Provider Access and Transaction Limits
Pix access, participant authorisation and a merchant acceptance contract are different questions. Identify the legal entity providing the service, its role and its responsible or settlement participant where applicable. Confirm their current status and the limits applying to the connection.
BCB's 2 October 2025 security presentation describes an accelerated application window from January to May 2026 for specified previously unauthorised institutions that joined after 30 June 2024. It also describes a R$15,000 initiation limit for unauthorised payment institutions and participants accessing RSFN through PSTIs, alongside exemptions and a route to request dispensation. This historical package is not a universal merchant cap or proof that every participant now has identical authorisation status.
Obtain the provider's applicable rules, any relevant exemption and its supported limits. Do not infer a blanket PSTI prohibition or universal daily allowance from that package. Merchant controls should use the contracted limits and handle rejections explicitly.
Cross-Border Collection Is a Separate Service
A proposal to let a Brazilian customer pay with Pix while an overseas merchant receives another currency needs an end-to-end money-flow diagram. Ask who collects the BRL, who performs foreign exchange, who pays the merchant, and which contract governs returns.
Confirm corridor availability, merchant eligibility, settlement currency, FX pricing and payout timing. A Pix logo at an overseas checkout is not sufficient evidence of a bilateral central-bank rail linkage or native interoperability with another country's system. Validate each offered corridor as a service; do not assume it is an automatic extension of domestic acceptance.
Apply the same discipline when comparing Pix with Mexico's SPEI: use the local provider's collection mechanics and a quote in the appropriate currency. The CoDi and Pix comparison examines different product journeys; it does not make one country's fees or permissions portable to the other.
Recurring Collection and Launch Criteria
Pix Automático adds a recurring-collection use case, but a one-off Pix integration does not establish access to every recurring function. Confirm consent, collection, retries, cancellation and refunds with the provider. The Pix Automático operations guide covers those distinct records and flows.
Before release, test successful collection, missing and duplicate callbacks, expired orders, return requests, failed returns, provider rejection and payout reconciliation against the merchant account. Record each result and exception owner. The launch decision should rest on a working money flow and understood costs, not a zero-fee assumption or national adoption headline.
Sources & methodology (4)
Pix transfers, merchant tariffs and MED scope; fee exemptions differ between individuals and companies
Checked:
API services cover charges, received Pix, linked returns and recurring collections; access depends on the receiving PSP contract
Checked:
The September 2025 security package had scoped authorisation deadlines and transaction-limit exemptions
Checked:
MED concerns suspected fraud and operational failures; recovery depends on the case and available resources
Checked:
Source types explained in our Methodology.
 By Shaun Toh · Director, Digital Payments · Razer